6:44
Tesco Profit Up 6.5% on Slower UK Sales: What Drove It?
Global signals by Andrew Dremin
7:57
Kraft Heinz $700M Investment: Can It Fix the Growth Engine?
3:13
Sainsbury’s & Morrisons: Why This Merger Is Easy to Defend but Hard to Monetise
4:24
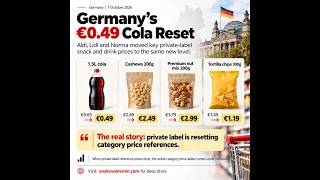
Germany’s €0.49 Cola Reset: How Discounters Break Grocery Pricing
5:25
The Spanish Grocery Paradox: Flat Volume, Surging Store Visits
6:24
Tesco Central Europe Exit: 2026 Case Study
7:10
PepsiCo Pricing Strategy: Why Price Cuts Failed (2026)
5:18
REWE Quick Commerce Strategy: Retail Media & Margins (2026)
6:27
Diageo 20% ABV Spirits: The 2026 Tesco Test
9:01
Grocery Retail Loyalty vs Market Share: 2026 Data
7:33
Mercadona’s Saturation Paradox: Spanish Grocery Market Share (September 2026)
7:38
UK Grocery Market Share: The Structural Split Between Lidl and Aldi
5:51
Mercadona vs. The Portuguese Market: The Limits of a Pure Private-Label Model
1:24
55% Footfall vs 7.4% Market Share: Mercadona’s Retail Paradox
Why Foreign Brands Fail in US Retail (The US Market Entry Illusion)
6:59
The Grocery Retail Paradox: France vs UK Grocery Strategy #retail
4:26
The €500M Olive Oil War: Spain, Italy, and the Fight for Retail Margins
6:26
Why Record Grocery Revenue Masks a Retail Crisis (EU-5 Breakdown)
6:46
Why Massive Megacities Bankrupt Global FMCG Brands
7:08
Why Chick-fil-A Makes 3x Subway’s Revenue with 80% Fewer Stores | Fast Food Economics
7:22
Why Expat Retirees Break Supermarket Planograms (And How Retailers Fix It)
9:03
Global Signals: Kantar BrandZ, Discounters, and the Real Cost of Complexity #retail
7:58
What Aviation Economics Teaches FMCG and Retail
9:53
US Grocery Retail Trends 2026: Why Real Volume Growth Matters More Than Inflation
8:29
UK Grocery Discounter Trends 2026: What the CMA Ruling Means for Aldi and Lidl
8:25
Why Mid-Tier Brands Are Disappearing in Retail (The Missing Middle)
6:04
A data-driven breakdown of the top 20 most valuable global food and beverage brands.